News and Announcements
Avenir Capital Quarterly Investor Letter; Fund up 2.8%
- Published February 08, 2016 11:17AM UTC
- Publisher Wholesale Investor
- Categories Company Updates
5th February 2016, Avenir Capital
The Avenir Value Fund (the “Fund”) increased 1.1%, net of fees and expenses, in the December 2015 quarter leaving the fund up 2.8% for calendar year 2015. The ASX All Ordinaries (including dividends) increased 3.8% for the year while the S&P 500 delivered 1.4%.
It was a rather frustrating year for our research driven, value-based approach. The companies we own continued to deliver against our investment thesis, solidly increasing underlying value throughout the year. Despite this, the market price placed on those companies showed little forward progress at best, or, in some cases, substantial declines. An investment strategy based on the simple principle of investing only when one is able to do so at a material discount to a conservative assessment of underlying or intrinsic value (broadly known as value investing) has suffered an unsatisfying few years.
Momentum investing, on the other hand, based on following trends without regard to fundamental value has worked all too well. As Seth Klarman, the famed Boston based value investor, noted in his recent 2015 letter for his Baupost fund:
“Momentum investing…worked brilliantly in 2015…buy what’s been performing well and watch it go even higher…By contrast, bottom up bargain hunting – which requires fastidious research, endless patience, pattern recognition skills derived from hard won experience and the application of sound judgement – didn’t prove profi table for us last year.”
Like many value investors, the public equity portfolio within Klarman’s $27 Billion Baupost fund suffered, declining 6.7% in 2015.
Now, it is not new to suggest that value investing does not deliver strong results in all periods. Value investors are known to require deep reserves of patience and discipline and can go for long stretches of time with no positive market affirmation of investment decisions. As Klarman says: “You don’t become a value investor for the group hugs”. It is this very fact however that makes value investing so powerful. If it worked all the time then it wouldn’t work over time because everyone would do it. Because only a few have the necessary temperament and operate in a business structure that allows them the luxury of acting consistently through the good times and the bad, the opportunity to make money by following a value strategy will always persist.
So, why have the eclectic, value-laden and increasingly valuable companies we, and other fundamentally based investors, own not yet been recognised by the market in a manner we feel appropriate?
To read the full article, please click here.
Company Updates
BlackRock has named the next Economy. What this latest paper means for Private Market Investors.
BlackRock has put a name on something the smart money has been circling for two years. Its digital assets research team calls it the machine-native economy. The thesis fits in one line. AI is machine-native intelligence. Digital assets are machine-native money. Both are built on the same architecture, and they are converging into a single […]
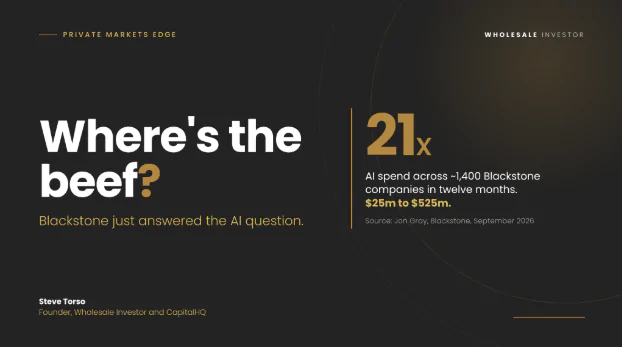
Where’s the beef? Blackstone just answered the AI question.
In 1984, a fast food ad asked a question that became a catchphrase. Where’s the beef? Jon Gray, President of Blackstone, used that line this month in front of global LPs. It is the question every capital allocator is asking about AI. Trillions of dollars are going into chips, data centres and power. That is […]
The Best of Both Worlds: How Omnique Fund is Rewiring Real World Assets via Tokenisation
For decades, the playbook for Australia’s wholesale investors has remained relatively unchanged: pick between the slow-moving, illiquid reliability of tangible assets like property and gold, or chase the frictionless, high-velocity liquidity of public equity and digital markets. But as macroeconomic volatility spikes and a structural housing deficit reshapes private debt demand, sophisticated investors are demanding […]
Backed By Leading Investment Groups and Family Offices